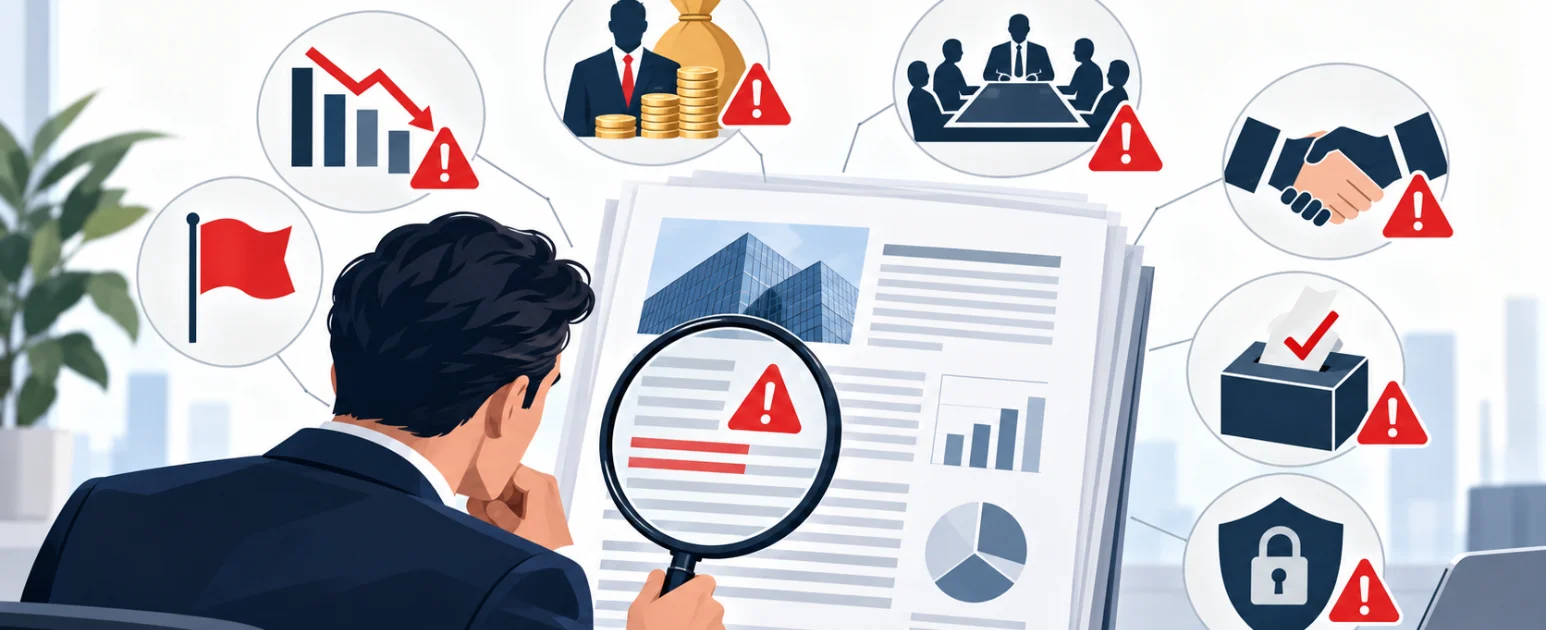
Suppose you’re reviewing a company’s proxy statement and suddenly notice something that does not look right. Executive pay increased after a weak year, several directors have close ties to management, or the company keeps doing business with insiders.
These can be warning signs. Common proxy statement red flags include weak pay-for-performance, changed bonus targets, poor board independence, related-party transactions, unequal voting power, unusual auditor fees, and weak insider ownership.
A red flag does not prove misconduct or mean the stock is a bad investment. It simply shows where investors may need to look more closely. This guide explains the main warning signs, where to find them in a DEF 14A, and what to check next.
Proxy Statement Red Flags Checklist at a Glance
Start your proxy review with executive incentives, board oversight, insider conflicts, voting power, and ownership. These areas can reveal governance risks that deserve closer investigation.
| Area to Review |
Potential Red Flag |
Where to Check |
| Executive Pay |
Pay rises while performance weakens |
CD&A, Summary Compensation Table, Pay versus Performance |
| Bonus Plans |
Targets or metrics are changed |
CD&A and executive compensation discussion |
| Executive Benefits |
Large special awards, perks, or severance |
Compensation tables and termination disclosures |
| Board Oversight |
CEO is chair with limited independent oversight |
Corporate governance section |
| Director Independence |
Long tenure, close connections, or excessive board commitments |
Director biographies and independence disclosures |
| Voting Power |
Dual-class shares or restrictive voting rules |
Voting and governance sections |
| Insider Dealings |
Transactions involving directors, executives, more than 5% beneficial owners, or immediate family members |
Related-party transactions |
| Auditor Relationship |
High or rising non-audit fees |
Auditor fees and audit committee section |
| Ownership |
Limited long-term insider ownership, hedging, or pledging |
Beneficial ownership and compensation sections |
| Shareholder Votes |
Significant prior opposition to executive pay or directors |
Prior voting results and board response |
One unusual disclosure is rarely enough on its own. Repeated patterns, weak explanations, and several connected red flags carry more meaning.
Executive Compensation Red Flags
Executive compensation becomes concerning when rewards appear disconnected from the results shareholders receive. For companies that provide a Compensation Discussion and Analysis (CD&A), it is one of the best places to understand how executives earn bonuses, stock awards, and long-term incentives.
Executive Pay Rises While Company Performance Falls
Rising executive pay during sustained weak performance can point to poor pay-for-performance alignment. Compare compensation with total shareholder return, net income, revenue, margins, cash flow, and the measures the company itself says matter.
The SEC’s Pay Versus Performance rules require covered companies to show the relationship between executive compensation actually paid and selected financial performance measures. The disclosure can include company TSR, peer-group TSR, net income, and a company-selected measure.
Also check the companies used as compensation peers. If management starts comparing pay with much larger companies, the benchmark for executive compensation may rise even when the business has not grown at the same pace.
Do not judge the issue from one bad year. A multi-year pattern of weaker results and rising rewards is more useful.
Performance Targets or Bonus Metrics Are Changed
Lowering performance hurdles or changing bonus metrics can make executive payouts easier to earn. This deserves closer attention when changes follow weak operating results.
Look for:
- - Lower revenue, earnings, or margin targets
- - Metrics replaced during the performance period
- - Large discretionary adjustments
- - Bonuses paid after original goals were missed
- - Heavy reliance on adjusted EBITDA or adjusted EPS
- - New exclusions that improve reported incentive performance
Non-GAAP measures are not automatically a red flag. The issue is whether the company keeps changing the measures or excluding costs in ways that make bonus targets easier to reach.
Special Bonuses, Excessive Perks, and Golden Parachutes
Large compensation outside the normal incentive plan deserves scrutiny when the company gives little performance-based justification. Special awards may be legitimate, but investors should understand why they were necessary.
Check for:
- - Retention or discretionary bonuses
- - Housing, relocation, or security benefits
- - High amounts under “All Other Compensation”
- - Accelerated equity vesting
- - Large severance or change-in-control payments (often called golden parachutes)
The useful question is whether the additional reward has a clear business purpose and reasonable connection to shareholder interests.
Clawback, Hedging, or Pledging Policies Need Review
Weak clawback and stock-risk policies can reduce the alignment between executives and shareholders. Hedging can reduce an executive’s exposure to a falling share price, while pledging stock as collateral can create additional risk.
Check how the clawback policy works and whether the company limits hedging or pledging. Also look at whether senior executives continue to hold meaningful company stock over time.
Board Independence and Governance Red Flags
Board governance becomes a concern when directors may lack the independence, authority, or time needed to challenge management. The proxy statement usually provides director backgrounds, committee roles, outside directorships, tenure, attendance, and independence determinations.
The CEO Also Serves as Board Chair
A CEO who also chairs the board concentrates management and board leadership in one person. That structure is not automatically poor governance, but investors should check what safeguards exist.
A strong lead independent director may offset some concerns. Review whether independent directors control executive sessions, board agendas, CEO evaluation, and communication with other directors.
The issue is not simply the job title. It is whether the rest of the board can provide credible independent oversight.
Long-Tenured, Connected, or Overboarded Directors
Long tenure, close management relationships, and excessive outside commitments can raise questions about effective independence. A director can meet formal independence rules while still having relationships worth reviewing.
Check director biographies for:
- - Long service with little board refreshment
- - Previous employment by the company
- - Business relationships with management
- - Family or other disclosed personal connections
- - Seats on several other public-company boards
Long tenure alone does not make a director ineffective. It becomes more relevant when combined with other signs of weak independent challenge.
Key Board Committees Lack Strong Independent Oversight
Weak independence on important committees can affect oversight of compensation, financial reporting, and board appointments. Focus on the audit, compensation, and nominating or governance committees.
Check who sits on each committee and whether the proxy discloses relationships that could affect independent judgment. The audit committee is particularly important when related-party transactions or auditor-independence questions appear elsewhere in the filing.
Shareholder Rights and Entrenchment Red Flags
Shareholder-rights concerns arise when governance rules give insiders strong control while making it harder for ordinary shareholders to influence the board. One provision may have a reasonable purpose, but several protections operating together can entrench management.
Dual-Class Shares Give Insiders Greater Voting Power
Dual-class share structures can give insiders far more voting power than their economic ownership suggests. Founder or management shares may carry several votes for every vote attached to publicly traded shares.
Compare the beneficial ownership table with actual voting rights. An insider may own a minority of the economic interest while retaining effective control of major shareholder decisions.
Staggered Boards and Voting Restrictions Limit Shareholder Influence
Staggered boards and restrictive voting provisions can make board changes more difficult. With a classified board, only a portion of directors face election each year.
Also check for:
- - Supermajority voting requirements
- - Limits on calling special meetings
- - Restrictions on action by written consent
- - Other rules that make shareholder-led changes harder
Review the provisions together instead of treating each one in isolation.
Poison Pills and Other Takeover Defenses Need Review
Takeover defenses deserve closer review when they make an unwanted acquisition much harder or more costly to complete. A shareholder rights plan, often called a poison pill, can make an acquisition more difficult to complete.
Check the trigger threshold, duration, board justification, and whether shareholders have any approval role. The concern is greater when the company already has several other protections that make management difficult to challenge.
Related-Party and Auditor Red Flags
Insider transactions and unusual auditor relationships can expose conflicts of interest that financial performance alone may not reveal. Proxy statements provide useful detail on both areas.
The Company Does Business with Insiders or Their Families
Related-party transactions deserve scrutiny when directors, executive officers, more than 5% beneficial owners, or their immediate family members have a financial interest in company business. Examples include leases, consulting agreements, family employment, loans, or purchases from businesses controlled by insiders.
Check:
- - Who receives the economic benefit
- - How large the transaction is
- - Why the company entered the arrangement
- - Whether alternatives were considered
- - Who reviewed and approved the deal
- - Whether the interested person stayed out of the approval process
Item 404 of Regulation S-K requires disclosure of certain related-person transactions when its requirements are met. Companies may also explain how these transactions are reviewed or approved.
A disclosed related-party deal is not automatically improper. Weak review procedures, repeated transactions, or unusually favorable terms deserve more attention.
High Non-Audit Fees Deserve Closer Review
High or rising non-audit fees can give investors a reason to look more closely at auditor independence. Review audit, audit-related, tax, and other fees across several years.
Tax or other permitted non-audit services do not automatically make the auditor less independent. The concern increases when non-audit work becomes unusually large or the audit committee gives little explanation about its oversight.
Share Ownership and Voting Signals to Check
Ownership patterns and previous shareholder votes can reveal whether insiders share investors’ economic exposure and whether governance concerns already exist. These signals work best when read alongside compensation and board disclosures.
Executives and Directors Hold Little Long-Term Ownership
Very low meaningful insider ownership may weaken the economic link between decision-makers and long-term shareholders. Compare actual beneficial ownership with the company’s stated ownership guidelines.
Do not automatically treat stock sales as a red flag. Executives may sell shares for taxes, diversification, or under scheduled trading plans, so the broader ownership pattern matters more than one transaction.
Say-on-Pay or Director Votes Receive Significant Opposition
Significant opposition in previous votes can show where shareholders have already challenged executive pay or board oversight. Look at prior say-on-pay results, director election votes, and the company’s response to shareholder feedback.
A weak vote matters more when the same issue appears again and the board has made little visible change. Final results from the current shareholder meeting are usually reported later in Form 8-K.
How to Verify a Proxy Statement Red Flag
A potential red flag should be checked against historical filings and other SEC disclosures before you draw a conclusion. Context helps separate a genuine pattern from an isolated or well-explained event.
Compare the Current DEF 14A with Previous Years
Year-over-year comparison can reveal changes that are easy to miss when you read only one proxy statement. Review both numbers and wording across several filing periods.
Compare:
- - Executive pay and incentive metrics
- - Special awards and perks
- - Director tenure and turnover
- - Related-party transactions
- - Previous shareholder opposition
A newly changed metric or relationship may be more informative than a figure that has remained stable for years.
Cross-Check the Issue with Other SEC Filings
Other SEC filings can confirm whether a proxy red flag reflects a wider financial or governance issue. Use the DEF 14A as one part of the research process.
Useful cross-checks include:
- - Form 10-K: Financial performance, risks, controls, and accounting context
- - Form 8-K: Executive departures, auditor changes, compensation events, and final voting results
- - Forms 3, 4, and 5: Reported insider ownership and transactions
- - Previous DEF 14A filings: Compensation and governance trends
Need easy access to SEC filings? Quantillium’s API for corporate filings includes a reliable proxy statements API to help you retrieve and track disclosure data efficiently. Check the API docs or start a free trial to get started.
Bottom Line
Sometimes one small disclosure can change how you see a company. That is why proxy statement red flags are worth checking carefully.
Look for weak pay-for-performance, poor board independence, insider deals, limited shareholder rights, and unusual voting or ownership patterns.
One red flag is not enough to judge a company. Compare past filings, check the context, and look for repeated patterns before you draw a conclusion.
Frequently Asked Questions
What are the biggest red flags in a proxy statement?
The main red flags include weak pay-for-performance, changed bonus targets, poor board independence, related-party transactions, unequal voting power, high non-audit fees, and weak insider ownership alignment.
Where can investors find executive compensation red flags?
Check the CD&A, Summary Compensation Table, Pay Versus Performance section, equity-award tables, and change-in-control disclosures. These sections show how executives are paid and what drives their rewards.
Is a CEO also serving as board chair a red flag?
Yes, it can be a red flag if the combined role weakens independent board oversight. The concern is lower when a strong lead independent director has clear authority.
What are related-party transaction red flags?
Related-party transaction red flags include repeated deals with insiders, unclear pricing, weak approval procedures, or transactions that appear to benefit executives, directors, or their family members.
Why should investors compare proxy statements year over year?
Comparing several years can reveal changing pay targets, rising perks, new insider relationships, board changes, or new voting restrictions. Trends often show more than one filing alone.